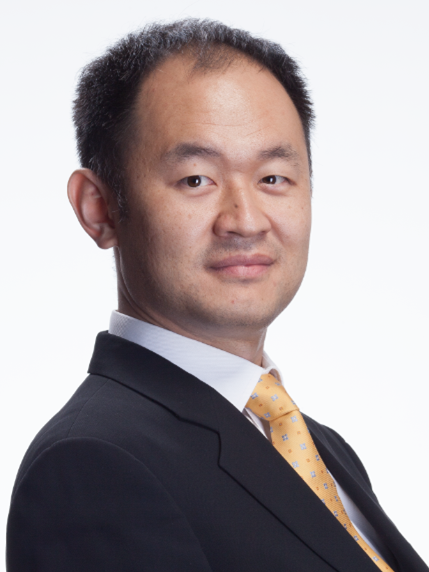
Jaehyuk Choi,男,博士,北京大學助理教授。
基本介紹
- 學位/學歷:博士
- 職業:教師
- 專業方向:定量金融、數學模型、數值方法、數據科學
- 外文名:Jaehyuk Choi
- 任職院校:北京大學
個人經歷,主講課程,研究方向,學術成果,
個人經歷
教育背景:
2005.6 美國麻省理工學院套用數學博士學位
2004.6 美國麻省理工學院斯隆商學院金融科技項目
2000.2 韓國科學技術學院數學學士
工作經歷:
2016.8—至今 北京大學滙豐商學院助理教授(深圳)
2013.4—2016.7 高盛集團定量分析師(香港)
2006.6—2013.3 高盛集團定量分析師(紐約)
2005.7—2006.5 法國巴黎銀行定量分析師(紐約)
主講課程
《隨機金融》
《定量金融研究:機器學習在金融的套用》
《套用隨機過程》
研究方向
定量金融、數學模型、數值方法、數據科學
學術成果
已發表論文:
J. Choi and S. Shin, Fast swaption pricing in Gaussian term structure models, Math. Finance (《數理金融》)26, 962 (2016), SSRN
J. Choi, M. Z. Bazant, and D. Crowdy, Diffusion-limited aggregation on curved surfaces, EPL (《歐洲物理快報》)91, 46005 (2010), Arxiv
J. Choi, K. Kim, and M Kwak, Numerical approximation of the implied volatility under arithmetic Brownian motion, Appl. Math. Finance (《套用數理金融》)16, 261 (2009), SSRN
D. Margetis and J. Choi, Iteration scheme by the Wiener-Hopf method for first-kind integral equations, Studies in Appl. Math(《套用數學研究》). 117, 1 (2006)
B. Davidovitch, J. Choi, and M. Z. Bazant, The average shape of transport-limited aggregates, Phys. Rev. Lett(《物理評論快報》). 95, 075504 (2005), Arxiv
J. Choi, A. Kudrolli, and M. Z. Bazant, Velocity profile of granular flows inside silos and hoppers, J. Phys.: Condens. Matter (《物理學雜誌:凝聚態物理》)17, S2533 (2005), Arxiv
J. Choi, D. Margetis, T. M. Squire, and M. Z. Bazant, Steady advection-diffusion around finite absorbers in two-dimensional potential flows, J. Fluid Mech(《流體力學期刊》). 536, 155 (2005), Arxiv
M. Z. Bazant, J. Choi, B. Davidovitch, and D. Crowdy, Transport-limited aggregation, Chaos(《混沌》)14, S6 (2004)
M. Z. Bazant, J. Choi, and B. Davidovitch, Advection-diffusion-limited aggregation, Chaos (《混沌》)14, S7 (2004) Chaos: An Interdisciplinary Journal of Nonlinear Science (《混沌:非線性科學的跨學科雜誌》)
J. Choi, A. Kudrolli, R. R. Rosales, and M. Z. Bazant, Diffusion and mixing in gravity-driven dense granular flows, Phys. Rev. Lett(《物理評論快報》). 92, 174301 (2004), Arxiv
M. Z. Bazant, J. Choi, and B. Davidovitch, Dynamics of conformal maps for a class of non-Laplacian growth phenomena, Phys. Rev. Lett(《物理評論快報》). 91, 045503 (2003), Arxiv
工作論文:
J. Choi, Sum of all Black-Scholes-Merton models: An efficient pricing method for spread, basket, and Asian options, SSRN (2017)
其他出版物:
J. Choi, Finance, Mathematics and Quants, Newsletter of the Korean Mathematical Society(《韓國數學學會學報》) 1, 1 (2014), [written in Korean]
