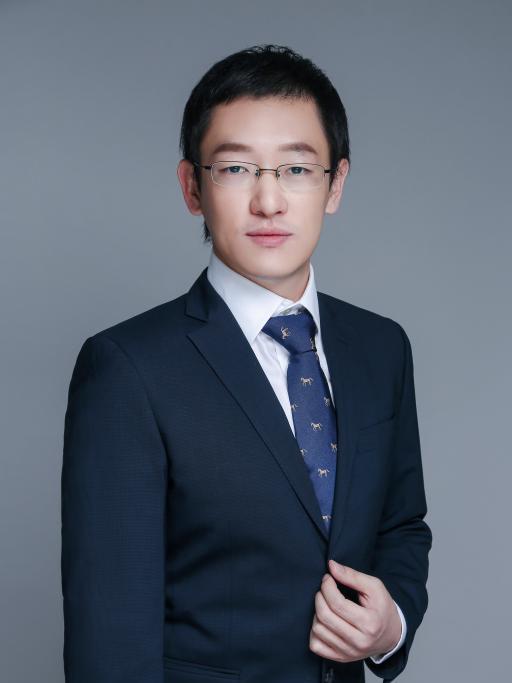
基本介紹
- 中文名:姚瀟
- 畢業院校:愛丁堡大學
- 學位/學歷:博士
- 職業:教師
- 就職學院:中央財經大學商學院
人物經歷,研究方向,學術成果,榮譽及獲獎經歷,
人物經歷
教育背景
2011.9—2015.1 管理科學博士, 信用風險方向
愛丁堡大學商學院信用研究中心
博士論文: “公司債券與銀行貸款的違約損失率模型”
2008.9—2011.7 運籌學碩士
中國科學院數學與系統科學研究院
碩士論文: “改進的支持向量機模型及其在信用風險評估中的套用”
2004.9—2008.7 套用數學學士
工作經歷
2018.9 至今 助理教授,中央財經大學商學院
2015.1-2018.7 高級分析師, 風險模型與分析組, 蘇格蘭皇家銀行。
教學經歷
2018.9 中央財經大學商學院
管理研究方法 (36學時)
2013.9—2014.6 愛丁堡大學商學院碩士生課程助教
SAS編程入門 (獨立授課,20學時)
信用風險管理 (助教,20學時)
研究方向
銀行與金融市場的信用風險,系統風險和金融穩定性,個人與企業徵信管理
學術成果
論文發表
[1] Zhiyong. Li, K. Li, X. Yao & Q, Wen (2019). Predicting Prepayment and Default Risks of Unsecured Consumer Loans in Online Learning. Emerging Markets of Finance and Trade,.
[2] X. Yao, J. Crook and G. Andreeva (2017). “Is It Obligor or Instrument That Explains Recovery Rate: Evidence from US Corporate Bond”, Journal of Financial Stability,
[3] X. Yao, J. Crook and G. Andreeva (2017). Enhancing Two-Stage Modelling Methodology for Loss Given Default with Support Vector Machines, European Journal of Operational Research,
[4] X. Yao, J. Crook and G. Andreeva (2015). “Support vector regression for loss given default modelling”, European Journal of Operational Research,
[5] Lean. Yu, X. Yao (2013). A total least squares proximal support vector classifier for credit risk evaluation. Soft Computing,
[6] Lean. Yu, X. Yao, Shouyang Wang, K.K. Lai (2011). Credit risk evaluation using a weighted least squares SVM classifier with design of experiment for parameter selection, Expert Systems with Applications, .
[7] 姚瀟, 余樂安 (2012). 模糊近似支持向量機模型及其在信用風險評估中的套用. 系統工程理論與實踐,
工作論文
X. Yao & Lean. Yu. A Novel Dual-Weighted Fuzzy Proximal Support Vector Machine with Application to Credit Risk Analysis
X. Yao & Lean. Yu, Least Squares Support Vector Regression Based on Fixed Margin Strategy, working paper
X. Yao, Default and recovery risk correlation: A case study of US corporate bonds.
學術會議報告
2014.10 Analyzing Corporate Bond Recovery Rates: An Empirical Study on the Impacts of Unobservable Firm Heterogeneity (分組報告)
2014 FMA Annual Meeting, Nashville, Tennessee, USA
2014.7 Two-Stage Modeling for Recovery Rates: A Case Study of UK Retail Credit Cards (分組報告)
20th Conference of the International Federation of Operational Research Societies, Barcelona.
2014.6 Use of SAS in PhD Research (邀請報告)
SAS Professionals Convention 2014, Marlow, UK.
2014.3 Modeling Loss Given Default in SAS/STAT (2014 SAS學生大使獎學金,分組報告)
SAS Global Forum 2014, Washington, D. C., USA.
2013.8 Predicting Loss Given Default: An Extension of Single Factor Model (分組報告)
Credit Scoring and Credit Control XIII, Edinburgh, UK
2013.7 Does Random Effect Make the LGD Predictions Better (分組報告)
26th European Conference on Operational Research, Rome, Italy
2010.10 A Fuzzy Proximal Support Vector Machine in Credit Risk Evaluation (分組報告)
9th Financial System Engineering and Risk Management Conference, Beijing, China
榮譽及獲獎經歷
2014 2014 SAS公司全球學生大使
2009 中科院優秀學生幹部
2007 教育部國家獎學金
2006 北京林業大學校一等獎學金
