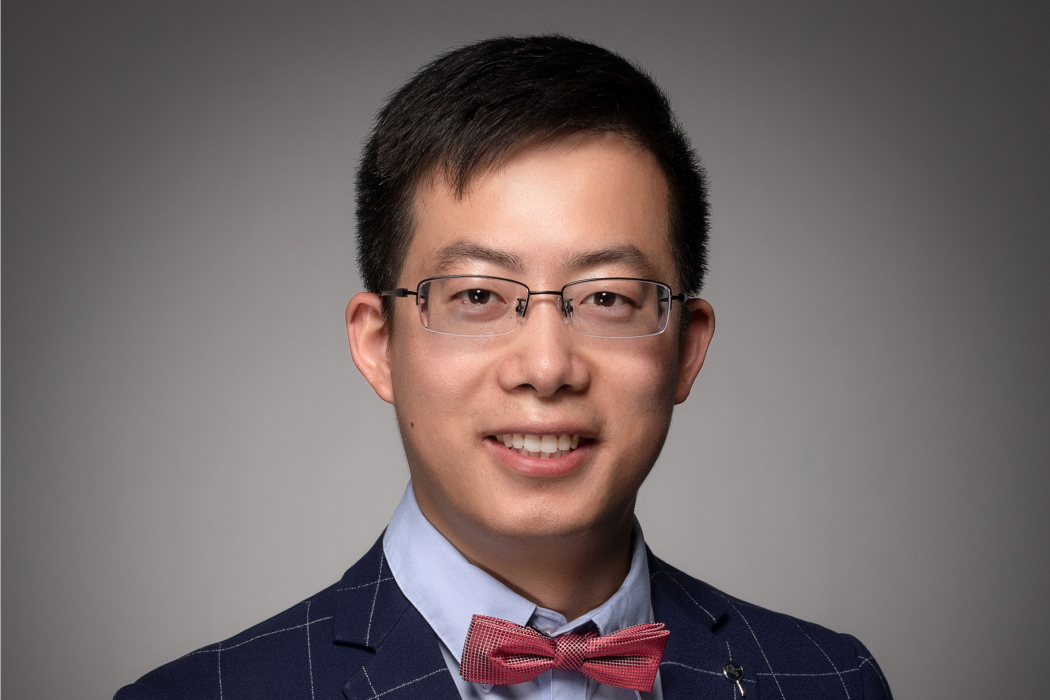
阮鑫豐,男,西交利物浦大學西浦國際商學院金融學高級副教授,主要研究領域為資產定價和衍生品。持有奧塔哥大學哲學博士學位(金融學專業,2017年)及西南財經大學運籌與管理碩士學位(2014年,研究方向:金融數學與金融工程)。
2017年獲博士學位後,阮鑫豐於2018年至2019年任奧克蘭理工大學博士後研究員,2019年至2023年任奧塔哥大學金融學講師、高級講師,2023年加入西交利物浦大學。在《Journal of Financial Markets》等SSCI期刊發表30餘篇論文,獲2019年奧塔哥商學院最佳新興研究者獎。主持江蘇省特聘教授研究基金項目,開展中國期權市場定價研究。現任《Journal of Chinese Economic and Business Studies》副主編,已指導6名博士生畢業。
基本介紹
研究方向,主要成就,
研究方向
資產定價和衍生品
主要成就
- Doing well while doing good: ESG ratings and corporate bond returns, with Sebastian Gehricke and Jin E. Zhang, Applied Economics, forthcoming.
- Risk-Neutral Moments and Return Predictability: International Evidence, with Jin E. Zhang and Junyu Zhang, Journal of Forecasting, forthcoming.
- Carr and Wu's (2020) framework in the oil ETF option market, with Xiaolan Jia and Jin E. Zhang, Journal of Commodity Markets, 2023, 31, 100334.
- Term spreads of implied volatility smirk and variance risk premium, with Sebastian Gehricke, Wei Guo, and Jin E. Zhang, Journal of Futures Markets, 43(7), 829-857.
- The COVID-19 risk in the cross-section of equity options, with Kanokrak Jitsawatpaiboon, Finance Research Letters, 2023, 53, 103684.
- Does short-term momentum exist in China? with Tianjiao Li and Tian Yue, Pacific-Basin Finance Journal, 2023, 77, 101920.
- VIX Option-Implied Volatility Slope and VIX Futures Returns, with Jungah Yoon and Jin E. Zhang, Journal of Futures Markets, 2022, 42(6), 1002-1038.
- The Price of COVID-19-Induced Uncertainty in the Options Market, with Jianhui Li and Jin E. Zhang, Economics Letters, 2022, 211, 110265.
- Corporate Governance and Firm-Level Jump and Volatility Risks, with Weihan Li and Haileslasie Tadele, Applied Economics, 2022, 54(22), 2529-2553.
- The COVID-19 Risk in the Chinese Option Market, with Sebastian Gehricke, Jianhui Li, and Jin E. Zhang, International Review of Finance, 2022, 22(2), 346-355.
- The Skewness Risk in the Energy Market, with Jungah Yoon and Jin E. Zhang, Journal of Risk and Financial Management, 2021, 14(12), 620.
- National Air Pollution and the Cross-Section of Stock Returns in China, with Sebastian Gehricke, Samuel Kirk-Reeve, and Jin E. Zhang, Journal of Behavioral and Experimental Finance, 2021, 32, 100572.
- Time-Varying Uncertainty and Variance Risk Premium, with Jin E. Zhang, Journal of Macroeconomics, 2021, 69, 103347.
- Specification Analysis of VXX Option Pricing Models under Lévy Processes, with Jiling Cao, Shu Su, and Wenjun Zhang, Journal of Futures Markets, 2021, 41(9), 1456-1477.
- Implied Volatility Smirk in the Australian Dollar Market, with Sebastian Gehricke, Connor Stuart, and Jin E. Zhang, Accounting and Finance, 2021, 61(3), 4573-4599.
- Dynamic Portfolio Choice and Information Trading with Recursive Utility, with Xingjiang Chen and Wenjun Zhang, Economic Modelling, 2021, 98, 154-167.
- The Implied Volatility Smirk in SPY options, with Sebastian Gehricke, Wei Guo, and Jin E. Zhang, Applied Economics, 2021, 53(23), 2671-2692.
- Choosing Factors for the Vietnamese Stock Market, with Nina Ryan, Jin E. Zhang, and Jing A. Zhang, Journal of Risk and Financial Management, 2021, 14(3), 96.
- The Economics of the Financial Market for Volatility Trading, with Jin E. Zhang, Journal of Financial Markets, 2021, 52, 100556.
- Ambiguity on Uncertainty and the Equity Premium, with Jin E. Zhang, Finance Research Letters, 2021, 38, 101429.
- The Implied Volatility Smirk of Commodity Options, with Xiaolan Jia and Jin E. Zhang, Journal of Futures Markets, 2021, 41(1), 72-104.
- Ambiguity, Long-Run Risks, and Asset Prices in Continuous Time, International Review of Economics and Finance, 2021, 71, 115-126.
- Left-tail risk in China, with Jin E. Zhang and Fang Zhen, Pacific-Basin Finance Journal, 2020, 63, 101391.
- Can the Relative Price Ratio of Gold to Platinum Predict the Chinese Stock Market? with Xing Han and Yongxian Tan, Pacific-Basin Finance Journal, 2020, 62, 101379.
- Asset Pricing in a Pure Exchange Economy with Heterogeneous Investors, with Jin E. Zhang, Mathematics and Financial Economics, 2020, 14(4), 605-634.
- Inferring Information from the S&P 500, CBOE VIX and CBOE SKEW Indices, with Jiling Cao and Wenjun Zhang, Journal of Futures Markets, 2020, 40(6), 945-973.
- Pricing VIX Derivatives with Infinite-Activity Jumps, with Jiling Cao, Shu Su, and Wenjun Zhang, Journal of Futures Markets, 2020, 40(3), 329-354.
- Volatility-of-Volatility and the Cross-Section of Option Returns, Journal of Financial Markets, 2020, 48, 100492.
- Moment Spreads in the Energy Market, with Jin E. Zhang, Energy Economics, 2019, 81, 598–609.
- A Note on “A Closed-form Pricing Formula for European Options under the Heston Model with Stochastic Interest Rate”, with Wenjun Zhang, Journal of Computational and Applied Mathematics, 2019, 350, 55-56.
- Pricing Swaps on Discrete Realized Higher Moments under the Lévy Process, with Wenli Zhu, Computational Economics, 2019, 53, 507–532.
- Equilibrium Variance Risk Premium in a Cost-free Production Economy, with Jin E. Zhang, Journal of Economic Dynamics and Control, 2018, 96, 42-60.
- Risk-Neutral Moments in the Crude Oil Market, with Jin E. Zhang, Energy Economics, 2018, 72, 583-600.
- Investor Attention and Market Microstructure, with Jin E. Zhang, Economics Letters, 2016, 149, 125-130.
- Equilibrium Asset Pricing under the Lévy Process with Stochastic Volatility and Moment Risk Premiums, with Jiexiang Huang, Jin E. Zhang, and Wenli Zhu, Economic Modelling, 2016, 54, 326-338.
- Real Option Model upon Dynamic Growth Process with Construction, with Nengsheng Fang and Caixiu Liao, Communications in Mathematical Sciences, 2015, 13(8), 2223-2239.
- Option Pricing Using the Fast Fourier Transform under Double Exponential Jump Model with Stochastic Volatility and Stochastic Intensity, with Jiexiang Huang and Wenli Zhu, Journal of Computational and Applied Mathematics, 2014, 263, 152-159.
- Exponential Stability of Stochastic Differential Equation with Mixed Delay, with Wenli Zhu, Jiexiang Huang, and Zhao Zhao, Journal of Applied Mathematics, 2014, Article ID 87037, 1-11.
- Pricing of American Put Option under a Jump Diffusion Process with Stochastic Volatility in an Incomplete Market, with Shuang Li, Yanli Zhou, and B. Wiwatanapataphee, Abstract and Applied Analysis, 2014, Article ID 236091, 1-8.
- Optimal Portfolio and Consumption with Habit Formation in a Jump Diffusion Market, with Wenli Zhu, Jin Hu, and Jiexiang Huang, Applied Mathematics and Computation, 2013, 222, 391-401.
- Equilibrium Asset and Option Pricing under Jump-Diffusion Model with Stochastic Volatility, with Wenli Zhu, Shuang Li, and Jiexiang Huang, Abstract and Applied Analysis, 2013,Article ID 780542, 1-13.
- Option Pricing under Risk-Minimization Criterion in an Incomplete Market with the Finite Difference Method, with Wenli Zhu, Shuang Li, and Jiexiang Huang, Mathematical Problems in Engineering, 2013, Article ID 165727, 1-9.
- Exponential Stability of Stochastic Nonlinear Dynamical Price System with Delay, with Wenli Zhu, Ye Qin, and Jie Zhuang, Mathematical Problems in Engineering, 2013, Article ID 168169, 1-9.
- Fast Fourier Transform Based Power Option Pricing with Stochastic Interest Rate, Volatility, and Jump Intensity, with Jiexiang Huang and Wenli Zhu, Journal of Applied Mathematics, 2013, Article ID 875606, 1-7.
- Continuous-Time Portfolio Selection and Option Pricing under Risk-Minimization Criterion in an Incomplete Market, with Wenli Zhu, Jiexiang Huang, and Shuang Li, Journal of Applied Mathematics, 2013, Article ID 175269, 1-11.
- Hedging Parameters of the Entropy Formula and Application to Dynamic Hedging, with Wenli Zhu, Journal of Sichuan University (Natural Science Edition), 2012, 25(5), 92-96. [阮鑫豐, 朱文莉, 熵定價公式的套期保值參數研究及其在動態對沖中的套用, 四川理工學院學報 (自然科學版), 2012, 25(5), 92-96.]
