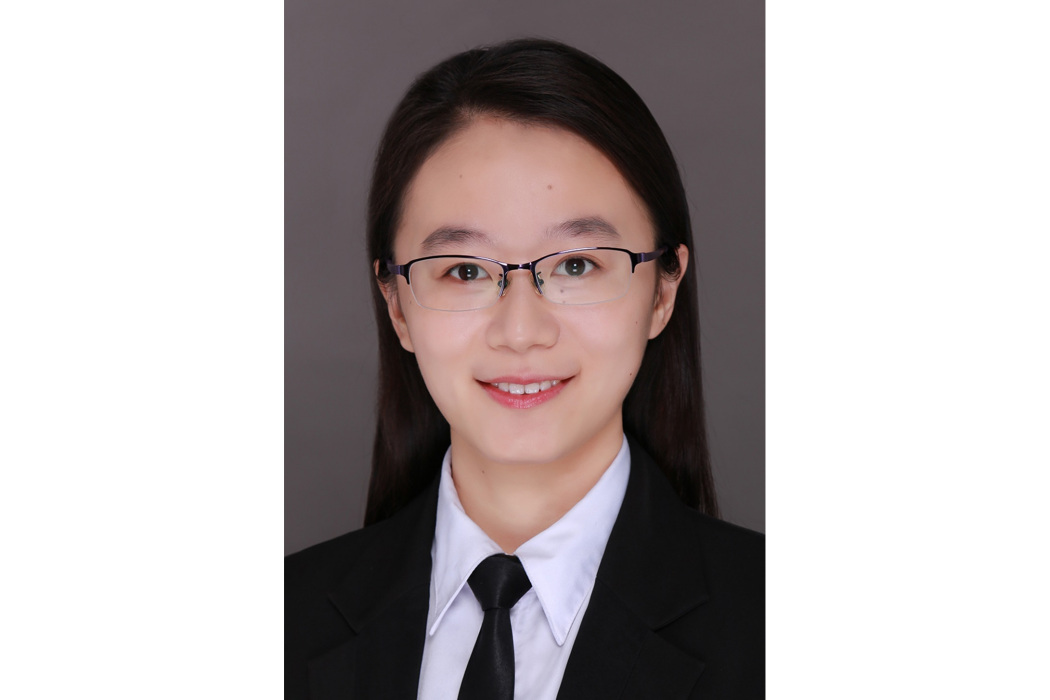
尹力博,女 ,管理學博士,中央財經大學金融學院教授,研究方向包括實證資產定價、金融市場 、大宗商品、能源金融 、金融工程。
基本介紹
- 中文名:尹力博
- 外文名:Libo Yin
- 國籍:中國
- 職業:教育科研工作者
- 教學職稱:教授
研究領域,工作經歷,學術兼職,主持課題,科研成果,資產定價,金融市場,大宗商品,
研究領域
實證資產定價 | 金融市場 | 大宗商品 | 能源金融 | 金融工程
工作經歷
2020年1月—2021年2月 中央財經大學 金融學院 教授
2015年11月—2019年12月 中央財經大學 金融學院 副教授
2017年9月—2018年9月 紐約州立大學石溪分校 訪問學者
2013年7月—2015年10月 中央財經大學 金融學院 講師
學術兼職
中國優選法統籌法與經濟數學研究會量化金融與保險分會 副秘書長\理事
主持課題
國家自然科學基金面上項目:金融化背景下國際原油市場多維信息含量研究——基於漣漪擴散雙重網路結構(71871234,2019年—2022年)
國家自然科學基金面上項目:考慮行為因素的多元耦合商品資產定價模型研究(71671193,2017年—2020年)
國家自然科學基金青年項目:大宗商品資產戰略配置模型研究(71401193,2015年—2017年,已結題)
中國人民銀行橫向課題:研究中國經濟轉型中通過金融渠道傳導的溢出效應(2016年—2017年)
中央財經大學“青年英才”培育支持計畫:金融化背景下原油市場不確定信息含量研究(QYP1901,2019年—2021年)
中央財經大學青年科研創新團隊計畫:不確定衝擊背景下大宗商品價格動態演化機理研究(2017年—2020年)
中央財經大學121人才工程青年博士發展基金:巨觀經濟不確定背景下國際大宗商品期貨市場信息傳遞研究(QBJ1416,2014年—2016年)
科研成果
資產定價
Libo Yin*, Ya Wei. Aggregate profit instability and time variations in momentum returns: Evidence from China[J]. Pacific-Basin Finance Journal, 2020, 60, 101276.
Libo Yin*, Huiyi Liao. Firm's quality increases and the cross-section of stock returns: Evidence from China[J]. International Review of Economics and Finance, 2020, 66, 228-243.
Libo Yin*, Ya Wei, Liyan Han. Firms' profit instability and the cross-section of stock returns: Evidence from China[J]. Research in International Business and Finance, 2020, 53, 101203.
Libo Yin*. Can the intermediary capital risk predict foreign exchange rates?[J]. Finance Research Letters, 2020, Forthcoming.
Xue Jiang, Liyan Han, Libo Yin*. Can skewness of the futures-spot basis predict currency[J]. Journal of Futures Markets, 2019, 39(11): 1435-1449.
Xue Jiang, Liyan Han, Libo Yin*. Currency strategies based on momentum, carry trade and skewness[J]. Physica A: Statistical Mechanics and its Applications, 2019, 517: 121-131.
Xue Jiang, Liyan Han, Libo Yin*. Can skewness predict currency excess returns?[J]. The North American Journal of Economics and Finance, 2019, 48: 628-641.
Libo Yin*, Tengjia Shu T, Zhi Su. Common idiosyncratic volatility and returns: From an investment horizon perspective[J]. International Journal of Finance & Economics, 2019, 24(1): 370-390.
Liyan Han, Xue Jiang, Libo Yin*. The predictive performance of the currency futures basis for spot returns[J]. Quantitative Finance, 2019, 19(3): 391-405.
Zhi Su, Tengjia Shu, Libo Yin*. The pricing effect of the common pattern in firm-level idiosyncratic volatility: Evidence from A-Share stocks of China [J]. Physica A: Statistical Mechanics and its Applications, 2018, 497: 218-235.
尹力博,廖輝毅.中國A股市場存在品質溢價嗎?[J].金融研究,2019, 10: 170-187.
尹力博,韋亞,韓復齡.中國股市異象的時變特徵及影響因素研究[J].中國管理科學,2019, 27(8): 14-25.
韓立岩,蔡立新,尹力博.中國證券市場的綠色激勵:一個四因素模型[J]. 金融研究,2017, 1: 145-161.
金融市場
Feng He, Ziwei Wang, Libo Yin. Asymmetric volatility spillovers between international economic policy uncertainty and the US stock market[J]. The North American Journal of Economics and Finance, 2020, 51, 101084.
You Wu, Libo Yin*, Liyan Han. Our currency, your attention Contagion spillovers of investor attention on currency returns[J]. Economic Modelling, 2019, 80: 49-61.
Yang Liu, Liyan Han, Libo Yin*. News implied volatility and long-term foreign exchange market volatility[J]. International Review of Financial Analysis, 2019, 61:126-142.
Zhi Su, Man Lu, Libo Yin*. Chinese stock returns and the role of news-based uncertainty[J]. Emerging Markets Finance and Trade, 2019, 55: 2949-2969.
Liyan Han, Yang Liu, Libo Yin*. Uncertainty and currency performance: A quantile-on-quantile approach[J]. The North American Journal of Economics and Finance, 2019, 48: 702-729.
Zhi Su, Tong Fang, Libo Yin*. Understanding stock market volatility: What is the role of US uncertainty?[J]. The North American Journal of Economics and Finance, 2019, 48: 582-590.
Qiuna Lv, Liyan Han, Yipeng Wan, Libo Yin*. Stock net entropy: Evidence from the Chinese growth enterprise market[J]. Entropy, 2018, 20: 805(1-22).
Liyan Han, Ziying Li, Libo Yin*. Investor attention and stock returns: International evidence [J]. Emerging Markets Finance and Trade, 2018, 51(14): 3168-3188.
Liyan Han, Yang Xu, Libo Yin*. Forecasting the CNY-CNH pricing differential: The role of investor attention[J]. Pacific-Basin Finance Journal, 2018, 49: 232-247.
Liyan Han, You Wu, Libo Yin*. Investor attention and currency performance: International evidence [J]. Applied Economics, 2018, 50(23): 2525-2551.
Yimin Zhou, Liyan Han, Libo Yin*. Is the relationship between gold and the U.S. dollar always negative? The role of macroeconomic uncertainty [J]. Applied Economics, 2018, 50(4):354-370.
Liyan Han, Yang Xu, Libo Yin*. Does investor attention matter? The attention-return relationships in FX markets [J]. Economic Modelling, 2018, 68: 644-660.
Zhi Su, Tong Fang, Libo Yin*. Does NVIX matter for market volatility? Evidence from Asia-Pacific markets [J]. Physica A: Statistical Mechanics and its Applications, 2018, 492: 506-516.
Ding Ding, Liyan Han, Libo Yin*. Structure of systemic risk and dynamics of contagion: A duplex inter-bank network [J]. Quantitative Finance, 2017, 17(9): 1435-1445.
Zhi Su, Tong Fang, Libo Yin*. The role of news-based implied volatility among US financial markets [J]. Economics Letters, 2017, 157: 24-27.
Libo Yin*, Liyan Han. Spillovers of macroeconomic uncertainty among major economics [J]. Applied Economics Letters, 2014, 21(13): 938-944.
Libo Yin*, Liyan Han. Macroeconomic uncertainty: Does it matter for commodity prices? [J]. Applied Economics Letters, 2014, 21(10): 711-716.
尹力博,吳優.離岸人民幣區域影響力研究—基於信息溢出的視角[J].金融研究,2017, 8: 1-14.
尹力博,李勍.投資者關注對人民幣匯率價差波動的影響研究——基於 GARCH-MIDAS模型[J]. 管理科學,2017, 30(5): 147-159.
尹力博,吳優.不確定衝擊與人民幣匯率動態演化——基於投資者關注的視角[J].金融經濟學研究,2017, 32(2): 3-19.
戴方賢,尹力博.股指期貨交易提升了股票市場有效性嗎?[J].財貿經濟,2017, 38(8): 36-51.
戴方哲,尹力博.證券分析師“變臉”行為會增加股票特質波動率嗎?[J].管理評論,2017, 29(5): 14-22.
戴方賢,尹力博.中國資本市場系統性風險——基於個股的風險聯動[J]. 投資研究,2017, 36(4): 75-89.
戴方賢,尹力博.分析師目標價預測是否引導了基金集中持股行為[J].投資研究,2016, 11: 134-150.
大宗商品
Libo Yin*, Jing Nie, Liyan Han. Intermediary asset pricing in commodity futures returns[J]. Journal of Futures Markets, 2020, Forthcoming.
Yang Liu, Liyan Han, Libo Yin*. Does news uncertainty matter for commodity futures markets? Heterogeneity in energy and non-energy sectors[J]. Journal of Futures Markets, 2018, 38: 1246-1261.
Liyan Han, Ziying Li, Libo Yin*. The effects of investor attention on commodity futures markets [J]. Journal of Futures Markets, 2017, 37(10): 1031-1049.
Libo Yin, Qingyuan Yang, Zhi Su*. Predictability of structural co-movement in commodity prices: the role of technical indicators [J]. Quantitative Finance, 2017, 17(5): 795-812.
Libo Yin*, Liyan Han. Macroeconomic impacts on commodity prices: China vs. the United States [J]. Quantitative Finance, 2016, 16(3): 489-500.
Libo Yin*, Liyan Han. Co-movements in commodity prices: Global, sectoral and commodity-specific factors[J]
Liyan Han, Yimin Zhou, Libo Yin*. Exogenous impacts on the links between energy and agricultural commodity markets[J]. Energy Economics, 2015, 49: 350-358.
Libo Yin*, Liyan Han. Exogenous shocks and information transmission in global copper futures markets [J]. Journal of Futures Markets, 2013, 33(8): 724-751.
大宗商品資產戰略配置模型研究,獨著,2017年6月,經濟科學出版社,22萬字.
尹力博,楊清元,韓立岩.技術指標能夠預測商品期貨價格嗎?來自中國的證據[J].管理科學學報,2018, 21(6): 99-109.
韓立岩, 鄭擎擎, 尹力博.商品金融化背景下大宗商品指數收益機制轉換[J].管理科學學報,2017, 20(9): 61-69.
尹力博,柳依依.中國商品期貨金融化了嗎?——來自國際股票市場的證據[J].金融研究,2016, 3: 189-206.
尹力博,柳依依.黃金是穩定的避險資產嗎?——基於巨觀經濟不確定性的視角[J].國際金融研究,2015, 7: 87-96.
蘇治,尹力博,付萱.公眾預期與量化寬鬆政策的衝擊效應:來自國際大宗商品的證據[J].世界經濟,2015, 10: 56-78.
蘇治,尹力博,方彤.量化寬鬆與國際大宗商品市場:溢出性、非對稱性和長記憶性[J].金融研究,2015, 3: 68-82.
尹力博,韓立岩.大宗商品戰略配置——基於國民效用與風險對沖的視角[J].管理世界,2014, 7: 39-51.
尹力博,韓立岩.國際大宗商品資產行業配置研究[J].系統工程理論與實踐,2014, 34 (3): 560-574.
韓立岩,尹力博.投機行為還是實際需求?——國際大宗商品價格影響因素的廣義視角分析[J].經濟研究,2012, 12: 83-96.
